No Fees
Unless We Win
Millions Recovered!
Seattle Wrongful Death Lawyer
Before a wrongful death lawsuit attorney can file anything in Washington, the court has to appoint someone to act for the person who died. Not the closest relative automatically, and not whoever was at the hospital. A personal representative, appointed through the estate. Families rarely know this, and insurance companies count on the delay.
Boohoff Law handles that step alongside the claim itself. Our Seattle office reviews these cases at no cost and works on a contingency fee, so a family that has just lost an income is not asked to pay legal fees to find out where they stand.
Available 24/7
Our specialists are here to listen and help for free, no strings attached.
877-999-9999
for a free consultation
Who Can File a Wrongful Death Lawsuit in Washington?
The personal representative of the deceased person’s estate files on behalf of the surviving spouse, domestic partner, children, or dependents. Individual family members do not file separately, even when the loss is theirs.
RCW 4.20.010 puts the right to sue with the personal representative. RCW 4.20.020 says who the recovery is for: the spouse, state registered domestic partner, and children, including stepchildren. If there are none, the action may be maintained for the benefit of the parents or siblings.
How Does Someone Become the Personal Representative?
Through a probate filing, usually in King County Superior Court. If there is a will naming an executor, that person is normally appointed. If there is no will, a family member petitions the court and is appointed administrator.
The process takes a few weeks when the paperwork is clean, and longer when relatives disagree. It happens whether or not the person who died owned much, because the appointment is what creates authority to bring the claim.
We coordinate this with families all the time, including when the estate itself is simple and the injury claim is the only real asset.
When the Family Does Not Agree on Who Should File
The court decides, using the priority the probate statutes set out. Disagreements slow things down, and they are more common than people expect when there are adult children from different marriages.
Addressing it early is better than filing a contested petition eighteen months in, with a deadline approaching.
What Is the Difference Between a Wrongful Death Claim and a Survival Action?
They are two claims from one death, and most Washington cases bring both.
The wrongful death claim compensates the family for what they lost when the person died: financial support, services, and the relationship itself.
The survival action belongs to the estate and covers what the person went through before they died. Under RCW 4.20.046, the personal representative may recover the deceased person’s own economic losses and non-economic damages, including “pain and suffering, anxiety, emotional distress, or humiliation personal to and suffered by the deceased.”
That distinction matters in a crash where someone survived for hours or days. Those hours are compensable, and they are compensable separately from the family’s loss.
What Can a Washington Wrongful Death Claim Recover?
 Two categories, and the second one is usually the larger.
Economic damages cover the money the family lost and spent: the income and benefits the person would have earned over a working lifetime, the value of the services they provided at home, medical bills from the final injury, and funeral and burial costs.
Non-economic damages cover the relationship. Washington juries may compensate a spouse for the loss of companionship and consortium, and children for the loss of a parent’s care, guidance, and love. There is no cap on these damages in Washington.
Calculating the economic side takes an economist in serious cases, because a 38-year-old’s future earnings, raises, and retirement contributions are not a number anyone should estimate by hand. Valuing a stay-at-home parent’s services takes the same care, and insurers routinely undervalue it.
Ask us what a claim like yours involves, with no obligation to hire anyone.
How Long Does a Family Have to File in Washington?
Three years from the date of death in most cases, under the state’s general injury limitation period. Waiting until the third year is risky, because the personal representative has to be appointed before the lawsuit can be filed, and that takes its own time.
Deaths involving a government vehicle, a city street design, a county road, or a public transit agency are different. Those require a formal tort claim to be presented to the agency first, with a waiting period before suit, and the window is significantly shorter.
A pending criminal case against the driver does not extend the civil deadline. The two run on separate tracks, and the civil claim often waits for the criminal case to finish while the clock keeps moving.
The Deaths That Become Claims in Seattle
Most of the Washington cases we see come from traffic. Head-on and high-speed collisions on I-5 and I-90, crashes involving commercial trucks where a driver was fatigued or the rig was poorly maintained, and people struck while walking or cycling in a crosswalk.
Workplace deaths bring a second layer. Washington’s workers’ compensation system through the Department of Labor and Industries covers the employment side, and it usually bars a suit against the employer, but a negligent third party on the job site, a subcontractor, a delivery driver, an equipment manufacturer, can still be liable.
Deaths on unsafe property and deaths caused by defective products round out the list, and both require preserving physical evidence quickly.
Insurance Limits Shape What a Family Can Recover
More than fault does, in many cases. A claim is only as collectible as the coverage behind it.
A private driver may carry a policy that does not come close to the value of a life, and Washington’s minimum limits are low relative to what a fatal crash costs a household. When that happens, other sources matter enormously.
The first is the family’s own underinsured motorist coverage, which can pay the difference between the at-fault driver’s limits and the actual loss. Policies held by the person who died, by a spouse, and sometimes by other household members may all apply, and they can be layered.
The second is a commercial policy. If the at-fault driver was working, delivering, or driving a company vehicle, an employer’s coverage usually stands behind them at much higher limits. Umbrella policies add another layer that people often forget they bought.
The third is a second responsible party. A property owner, a contractor, a vehicle owner who lent the car, or a manufacturer whose component failed each bring their own insurance.
Finding all of it early is what determines whether a case is worth litigating and what a reasonable settlement looks like. We ask for policy limits and declarations pages at the outset, and we keep looking after the first policy is identified.
Why Do Insurers Move So Fast After a Fatal Crash?
Because the first weeks are when a family is least able to evaluate an offer. An adjuster who reaches a grieving spouse before a lawyer does can sometimes close a claim for a fraction of its value, with a signed release that cannot be undone.
Two patterns show up over and over. The first is the quick offer, framed as help with funeral costs. The second is delay, where the carrier goes quiet for months hoping the family gives up or misses a deadline.
Neither has anything to do with what the claim is worth. Both work often enough that they remain standard practice.
We ask carriers for the full policy limits and the declarations pages early, because a family deciding whether to accept an offer deserves to know how much coverage exists before they answer.
What a Family Should Do in the First Weeks
Very little, legally, beyond protecting a few things while the rest can wait.
Keep the documents that arrive: the police or incident report number, the medical records and bills, the death certificate once it is issued, and any correspondence from an insurance company. Put them in one place rather than answering each one as it comes.
Do not sign anything from an insurer, including a release, a medical authorization, or a settlement of any size, until someone has reviewed it. A broad medical authorization lets a carrier go through years of unrelated history looking for something to use.
Stay off social media about the case, and ask relatives to do the same. Insurers look, and a post meant for family gets read very differently in a claim file.
Preserve physical evidence where you can. The vehicle should not go to salvage, and a workplace or product involved in the death should not be altered.
Then take your time. The claim will still be there in three weeks, and the only real deadline in the first month is preventing evidence from disappearing. Everything else, including the decision about whether to hire anyone, can wait until the household has caught its breath.
How a Wrongful Death Case Moves Forward
In four phases, and the first is the one families do not expect.
The appointment phase comes first. A petition opens the estate and the court appoints a personal representative, which creates the authority to act. This is paperwork, and we handle it alongside the family.
The investigation phase runs in parallel. Reports, video, vehicle or scene evidence, witness interviews, and the full set of insurance policies that could respond. Where there is a criminal case, we follow it, since the evidence developed there can support the civil claim.
The valuation phase is where the case becomes real. Economic losses get calculated by professionals: lifetime earnings and benefits, household services, and the cost of what the family now has to replace. The non-economic side requires talking with the people who knew the person, because a jury cannot value a relationship it has never heard described.
Then negotiation, and litigation if that fails. Filing a lawsuit does not mean a trial. Most cases resolve at mediation or shortly after depositions, though carriers move much further when they believe a family is prepared to go the distance.
Does a Settlement Get Taxed, and Who Gets Paid First?
Compensation for personal physical injuries and for a wrongful death is generally not treated as taxable income under federal law, though interest and certain other components can be. Anyone in this position should get that confirmed by a tax professional for their own situation.
Before a family sees money, several claims may attach to the recovery. Medical providers who treated the final injury, health insurers with reimbursement rights, Medicare or Medicaid where they paid, and in workplace deaths, the workers’ compensation carrier.
Those amounts are frequently negotiable, and reducing them is part of the work. A settlement that looks strong on paper can shrink badly if nobody pushes back on the liens attached to it.
The court also reviews how the recovery is divided among beneficiaries in many cases, and any share belonging to a minor child is usually placed in a protected account until adulthood.
How We Handle a Seattle Wrongful Death Case
We take the mechanics off the family. Our office requests the collision or incident reports, secures video and vehicle evidence before it is lost, identifies every insurance policy that could apply, and handles the probate coordination so the personal representative is appointed without the family chasing forms.
Then we build the human side of the case, which is the part that actually determines value. That means talking to the people who knew the person: employers, coworkers, coaches, neighbors. A wage statement proves income. It does not prove what a household lost, and that is what a jury is being asked to understand.
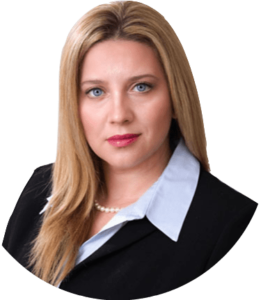
Boohoff Law has an office at 920 5th Avenue, Suite 1530, in downtown Seattle. Founder Tatiana Boohoff is admitted in Washington and Florida and is a Life Member of the Million Dollar Advocates Forum. Our team works in English and Spanish, and we meet families at home when coming to an office is too much.
There is no charge for the first conversation, and our fee is a percentage of the recovery, set in writing before we start.
No Fees. Unless We Win.
We’re here for you. Reach out whenever you are ready, day or night.
Questions Families Ask Us After a Fatal Accident
No. The civil claim is separate and can proceed on its own schedule, though there are strategic reasons to let parts of the criminal case play out, especially when the prosecution is developing evidence your claim can use. What cannot happen is waiting so long that the civil deadline passes. A criminal conviction does not restart it.
Possibly. Washington recognizes what courts call a committed intimate relationship, which can give an unmarried partner property rights in some situations, though wrongful death beneficiary status is defined narrowly by statute. These situations need to be looked at individually and early, because the answer shapes who has to be appointed and what can be claimed.
The personal representative distributes it among the statutory beneficiaries, and when there is more than one, the split reflects each person’s actual loss rather than an automatic equal share. A court reviews the allocation in many cases, and any distribution involving a minor child requires court approval and usually a protected account.
No. Life insurance is a benefit your family paid for, and it does not offset the responsible party’s liability. The same is generally true of employer death benefits. An insurer that argues otherwise is testing whether you know that.
It can be. The question is medical causation, whether the injuries from the crash led to the death, and that is established through records and treating physicians rather than the calendar. The survival claim for what he endured during those months runs alongside it.
Yes. Lost earnings are only one part of a wrongful death claim, and often not the largest. The law recognizes the value of the services a person provided, including childcare, household work, and care for a spouse, along with the loss of their companionship, guidance, and relationship with the people who survive them.
Those damages do not depend on a paycheck, and cases involving retirees and stay-at-home parents are valued on exactly that basis.
When You Are Ready, We Will Take It From Here
There is no version of this where a legal claim makes things right. What it can do is keep a household stable, cover what the loss actually cost, and put the responsibility where it belongs.
If you want to know where your family stands, send us what you have. We will explain the steps in order, tell you what the deadlines are, and give you a straight answer about whether a claim makes sense.
For families whose loss came from medical care, the answers are different, and our Seattle medical malpractice lawyer page covers that ground. If you are still working through the first days after a fatal crash, we have a guide on the steps after a fatal car accident in Seattle.
Contact Boohoff Law for a free, private consultation.

Recovery is personal.

We’re here for you.
We’re close by. And if you can’t make it to us, we’ll meet you where you need us, at home or in the hospital.
© 2025 Boohoff Law, P.A. — Auto Accident Lawyers.
The information on this website is for general information purposes only. Nothing on this site should be taken as legal advice for any individual case or situation. This information is not intended to create, and receipt or viewing does not constitute, an attorney-client relationship.
Disclaimer: The results and testimonials presented on this website are based on the unique facts and circumstances of each case. Past results do not guarantee or predict similar outcomes in future cases. Every legal matter is different, and you should not rely on prior case results as an expectation of future performance.
